Must Know Topics before you become Non-Resident Indian (NRI)
Things I Wish I Knew Before Becoming a Non-Resident Indian (NRI)
As an Indian NRI expat living in a Nordic country for the last 14 years, the most important things I have learned and practically experienced are:
-
You need to convert your Indian resident bank account to a Non-Resident Account as per FEMA rules.
-
NRIs can’t open a PPF (Public Provident Fund) in India.
-
PPF accounts opened while you were a resident in India can’t be extended after 15 years once you become an NRI.
-
Sukanya Samriddhi Yojana accounts can’t be held by NRIs.
-
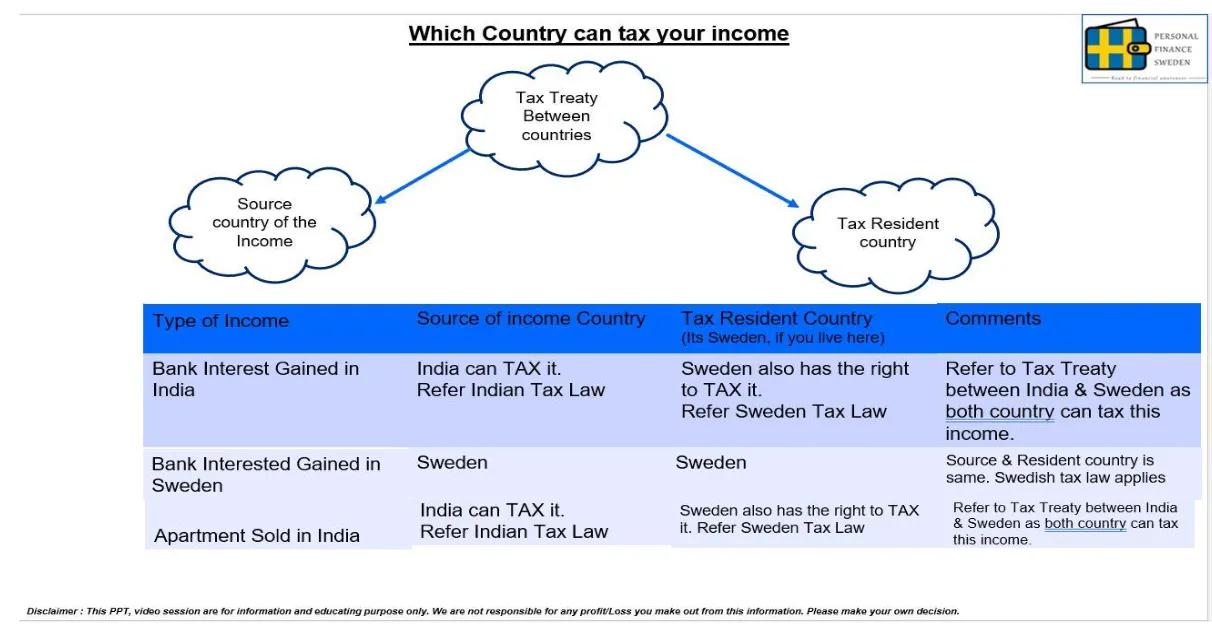
Understand the Tax Treaty (Double Tax Avoidance Agreement): Ensure you know the tax treaty between India and your current country of residence.
-
If you withdraw EPF (Employee Provident Fund) money in India after moving abroad, note that EPF may be tax-free in India but could be taxable in your country of residence. (Check the tax treaty.)
-
If you quit your Indian job and move abroad, consider converting your Indian company group healthcare policy into a private medical policy for you and your family. It’s good to maintain medical insurance in India.
-
Check with your life insurance provider to confirm whether your policy remains valid after moving to a new country. Obtain written confirmation.
-
Update the status of your investments, mutual funds, LIC policies, and Demat accounts to NRI.